IR Information
Semiconductors Overview of Segments Fuji Electric Report 2026

03 / SEMICONDUCTORS — Overview of Segments

Semiconductors

Toru Hosen, Director and Senior Managing Executive Officer, Corporate General Manager, Semiconductors Business Group
Director and Senior Managing Executive Officer
Corporate General Manager, Semiconductors Business Group
Toru Hosen

We will strive for medium- to long-term business expansion by securing design wins and developing new customers while establishing production systems aligned with demand.

MARKET

Market Trends and Business Opportunities

Power semiconductors, which contribute to energy savings through high conversion efficiency and power control, are experiencing increased global demand against the backdrop of environmental measures for decarbonization and rising investment in automation within the manufacturing industry.

SubsegmentMarket Trends and Business Opportunities
Industry In the motor drive field, which includes inverters and servos, demand for semiconductor production equipment and industrial robots is expected to increase in step with growing demand for AI semiconductors, while demand for automation and efficiency improvements for NC machine tools is expected to continue. In the renewable energy field, demand for wind power generation and storage battery systems is expected to remain strong.
Automotive Demand for both battery electric vehicles (BEVs) and hybrid vehicles (HEVs/PHEVs) is expected to continue to increase.
PERFORMANCE

Overview of Results

In fiscal 2025, despite downward pressure on sales from lower demand for Si products for electrified vehicles and the impact of the selling price revisions in the previous fiscal year, net sales increased by ¥0.6 billion year on year to ¥237.4 billion, mainly due to increased demand centered on renewable energy in China, higher demand for SiC products for electrified vehicles, and favorable foreign exchange impacts. Operating profit decreased by ¥13.6 billion year on year to ¥23.5 billion. Although sales in the industrial field increased, earnings were affected by higher raw material prices, price competition centered on the Chinese industrial market, lower sales in the automotive field, and the impact of the selling price revisions in the previous fiscal year.

In fiscal 2026, although demand is expected to increase for data centers and semiconductor production equipment in the industrial field and for SiC products for electrified vehicles, we plan for net sales of ¥225.0 billion, down ¥12.4 billion year on year, mainly due to lower demand from European and U.S. customers in the automotive field and unfavorable foreign exchange impacts. We plan for operating profit of ¥13.0 billion, down ¥10.5 billion year on year, due to higher raw material prices and lower sales in the automotive field.

Business Performance Trends

(Billions of yen)

FY2025 Achievements

  • Expansion of sales through investment to increase SiC front-end production capacity (vs. previous fiscal year: 2.5x SiC production capacity; approximately 2x SiC net sales)
  • Start of mass production and sample shipments of new products (Mass production: large-capacity IGBT modules for renewable energy, SiC chips for electrified vehicles, compact RC-IGBT modules)
    (Samples: 8th-generation IGBT modules)

FY2026 Challenges

  • Growth of sales and acceleration of new initiatives for promoting Fuji Electric's specifications
  • Development of competitive new products
  • Enhancement of manufacturing
CAPEX & R&D

Plant and Equipment Investment and R&D Expenditures

Plant and Equipment Investment

(Billions of yen)

R&D Expenditures

(Billions of yen)
* Figures for R&D expenditures are classified by segment according to theme and therefore differ from the figures stated in the consolidated financial report.

Key Plant and Equipment Investment Plans

  • Development of production lines for 8-inch SiC devices
  • Increase in module production capacity for industrial and automotive applications (to support new products)
  • Updates to ultrahigh voltage substation

Key R&D Plans

  • SiC (next-generation, 8-inch)
  • 8th-generation IGBT
PRIORITY MEASURES

Priority Measures

Strengthen Efforts to Secure New Design Wins and Develop New Customers to Expand Sales

The Company has industry-leading low-loss chips that contribute to higher efficiency, smaller size, and higher reliability in power electronics products such as inverters, as well as packaging technologies that achieve high heat dissipation and high reliability. Through customer support utilizing our global production bases and sales and design centers, we hold a leading position in the IGBT module market, having the third highest share globally.

Leveraging these strengths in our power semiconductor business, we will steadily secure new design wins and develop new customers, primarily in the motor drive and renewable energy fields and for electrified vehicles, where medium- to long-term market growth is expected.

In the industrial field, we aim to grow sales faster than the market by expanding sales of new products. In the automotive field, we will drive sales growth from fiscal 2028 onward through new customer development and securing design wins.

New Product Development and Mass Production to Strengthen Competitiveness

We will continue to develop new products to address advanced technical needs such as equipment downsizing, lower system costs, and higher efficiency.

In the industrial field, we will mass-produce 8th-generation IGBT modules that reduce power loss by at least 15% compared to the 7th generation and increase rated current within the same package. We will also develop a new medium-capacity module differentiated by our proprietary packaging technology and that is optimized for the intermediate range between medium- and large-capacity applications, providing products ideally suited to customer equipment for renewable energy, data centers, and other markets that are expected to grow over the medium to long term.

In the automotive field, we will mass-produce high-power SiC modules that achieve a smaller size and a lower profile through our proprietary three-dimensional wiring technology while significantly reducing inductance* inside the module. We will also begin sample shipments of next-generation low-profile-package SiC modules that enable a broad product lineup of ratings within a single package. These new products will help customers reduce the size and cost of their equipment.

* Inductance: A higher value here increases switching loss and noise

New Products for the Industrial Field
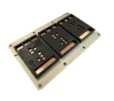
New Medium-Capacity Module
Strengths/FeaturesCompact package (footprint 49% smaller than large-capacity modules)
Lower inductance accommodates mounting of SiC chips
Applications (Examples)Renewable energy, data centers, etc.
New Products for xEVs (SiC Module)
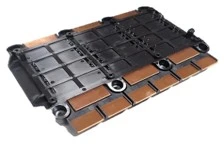
High-Power Module
High-Power Module
Strengths/FeaturesCompact, short package (Volume: -49% vs. conventional product)
Low inductance (Inductance: -80% vs. conventional product)
Adopting Vehicles Types (Examples)Large vehicles, sports vehicles
Next-Generation Low-Profile Module
(Example of combined application)
Strengths/FeaturesA wide range of ratings available in a single package
Support for diverse inverter circuit configurations
Adopting Vehicles Types (Examples)Compact vehicles, mid-size vehicles, large vehicles

Building an Optimal Production System to Meet Demand

In the chip manufacturing process (front-end), we will increase SiC production capacity in line with demand, prepare for mass production of 8th-generation IGBTs, and scale back small-diameter production lines. For SiC, following the Tsugaru Factory, we will begin 6-inch production at the Matsumoto Factory while moving forward with preparations for mass production of 8-inch devices. For Si, we will systematically scale back and close small-diameter lines of 6 inches or less and shift production to 8-inch lines, thereby improving productivity, promoting rationalization, and strengthening profitability.

In the assembly process (back-end), we will launch mass production of new products and expand production capacity to meet rising demand. At our bases in Japan, we will start production of 8th-generation IGBT modules for the industrial field and new SiC modules for the automotive field, and we will increase production capacity for large-capacity industrial modules and compact IGBT modules for electrified vehicles. At overseas bases in China, Malaysia, and elsewhere, we will increase production capacity for 7th-generation IGBT modules, for which global demand remains strong, by 20% to 30% year on year, thereby establishing a structure that can reliably meet increased demand in the industrial field.

Latest IR Materials

Contact Us